A £435k first charge loan at 60% LTV, repaid within six months.
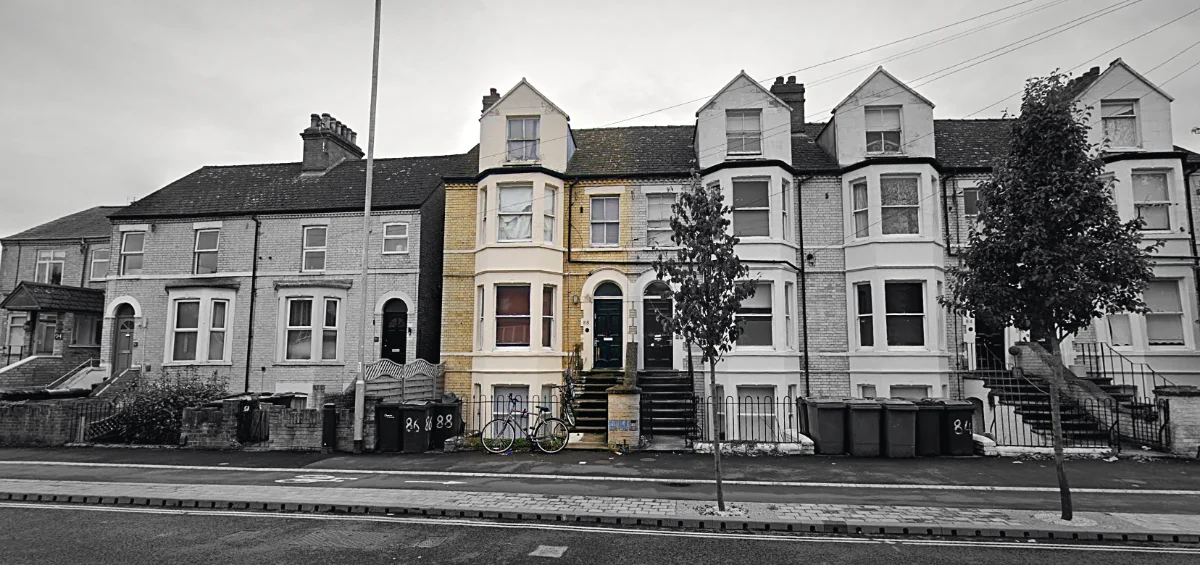
Acquisition of 88 Milton Road, a 173 m² freehold building in Cambridge CB4, already arranged as three self contained flats (two 2 beds and a 3 bed), at £525,000. The identical house next door, 86, made £735,000 at auction in July.
Currently in legals at an agreed price of £525,000, with the valuation in at £725,000. We're looking for a private lender to provide a £435,000 first charge loan to fund the purchase. The balance of the purchase costs, c.£135,000, comes from Promoveo and a second charge lender ranking behind this loan. We're looking to complete within 2 to 3 weeks.
£45,000 fixed, protected if we repay early.
We're aiming to exit ahead of the 6 month term. The full return is protected either way, so an early exit only shortens the time the capital is tied up, without impacting the return.
Headline terms
| Loan | £435,000 net |
| Term | 6 months |
| Return | £45,000 fixed (1.72% per month) |
| Minimum return | The full 6 months' return is payable even if the loan is repaid early |
| Repayment | Loan and return paid in full at redemption, by month 6 at the latest |
| Default rate | 2.5% per month on the outstanding balance for any period beyond month 6 |
| Security | First legal charge over the property, plus personal guarantees from the company directors |
| Valuation | £725,000 (60% LTV) |
What the lender receives
| Repaid at | Return | Total repaid | Per month |
|---|---|---|---|
| Month 4, route one sale | £45,000 | £480,000 | 2.59% |
| Month 6, latest | £45,000 | £480,000 | 1.72% |
Per month is the return as a monthly rate on the £435,000 advanced, for the time the capital is actually out. Any period beyond month 6 runs at the 2.5% per month default rate on the outstanding balance.
A first charge at 60% LTV, and £245k of headroom.
The loan is advanced to the purchasing company and secured by a first legal charge over the property, with personal guarantees from the company directors. Nothing ranks ahead of it; the second charge lender sits behind under a deed of priority.
At the £725,000 valuation the loan is 60% LTV, and the loan plus the full £45,000 return is 66%, leaving £245,000 of headroom. A sale at the £730,000 guide covers the £480,000 redemption 1.52 times; even at 84's July auction result of £682,500 it is covered 1.42 times.
Three ways to repay, all inside the six month term.
Redemption is £480,000: the £435,000 loan plus the £45,000 return. Route one is a sale of the building as it stands within c.4 months, by direct sale first and then at auction. If it hasn't sold by month 3, route two refinances this loan onto a term facility and a development facility, repaying it by month 6 at the latest.
Direct sale, as it stands
Sell the building as bought, arranged as three flats, at a £730,000 guide on a c.4 month hold. The sale proceeds repay the loan and the £45,000 return.
Auction, as it stands
The quickest route. Auction sales complete in 28 days, well inside the term, and 84 and 86 next door sold at the same Allsop sale in July. Cover is shown at 84's result, the lower of the two.
Refinance by month 6
Only if the building does not sell. If it hasn't sold by month 3, we refinance onto a term facility and a development facility, which repay this loan in full by month 6 at the latest and fund a £165,000 refurbishment. We then hold and let the three flats, in a city with rental vacancy around 2%.
84 & 86 sold at auction in July. They're the direct comparables.
The valuation and the route one guide both sit on evidence from Milton Road itself. 84 and 86, next door, sold at auction in July.
The dashed line is our agreed purchase price, £525,000. Lighter caps on the columns show the top of the evidenced range. Sources: HM Land Registry price paid data; Allsop residential auction results, 30 July 2026 (lots 54 & 55). The valuation for lending purposes is £725,000. Other values that are not completed sales are guides.
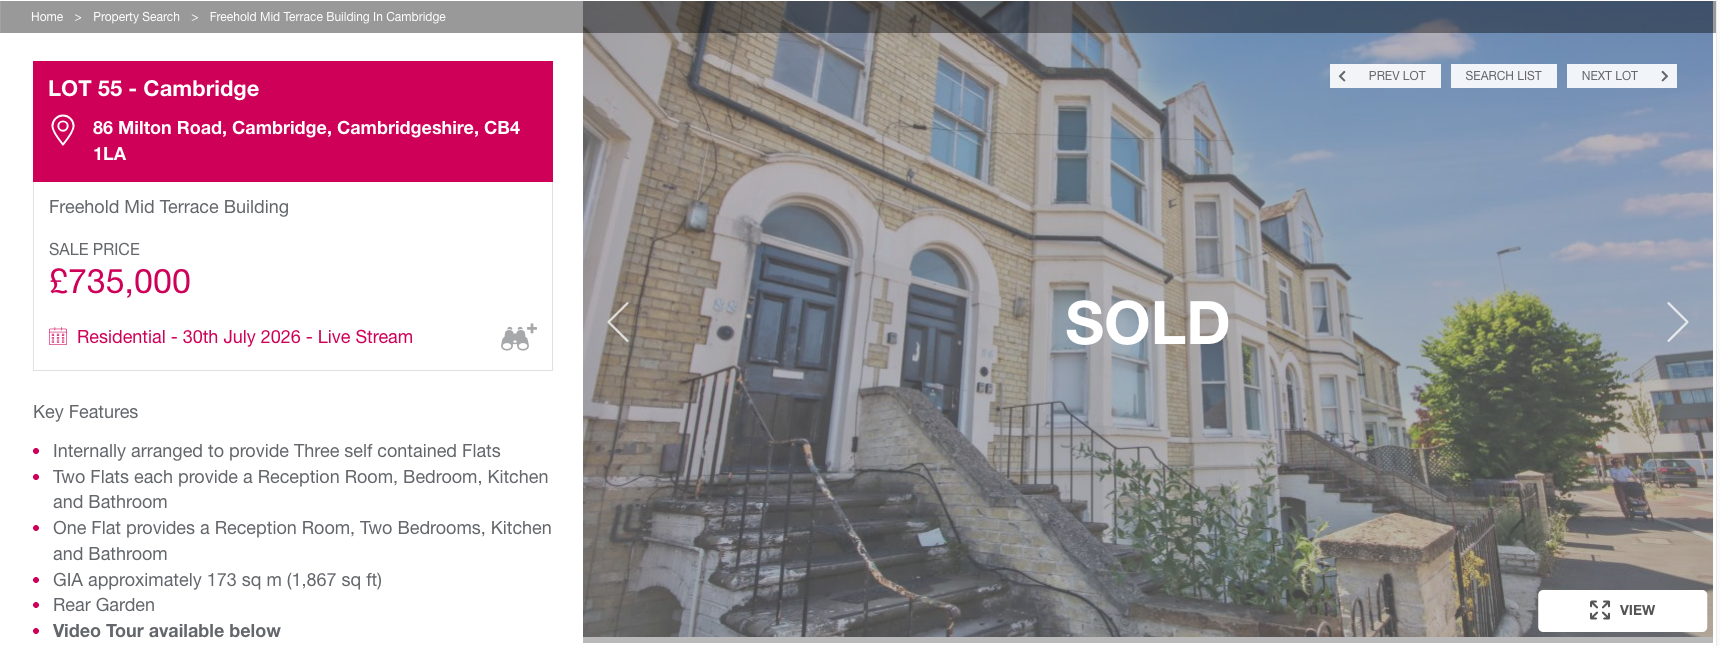
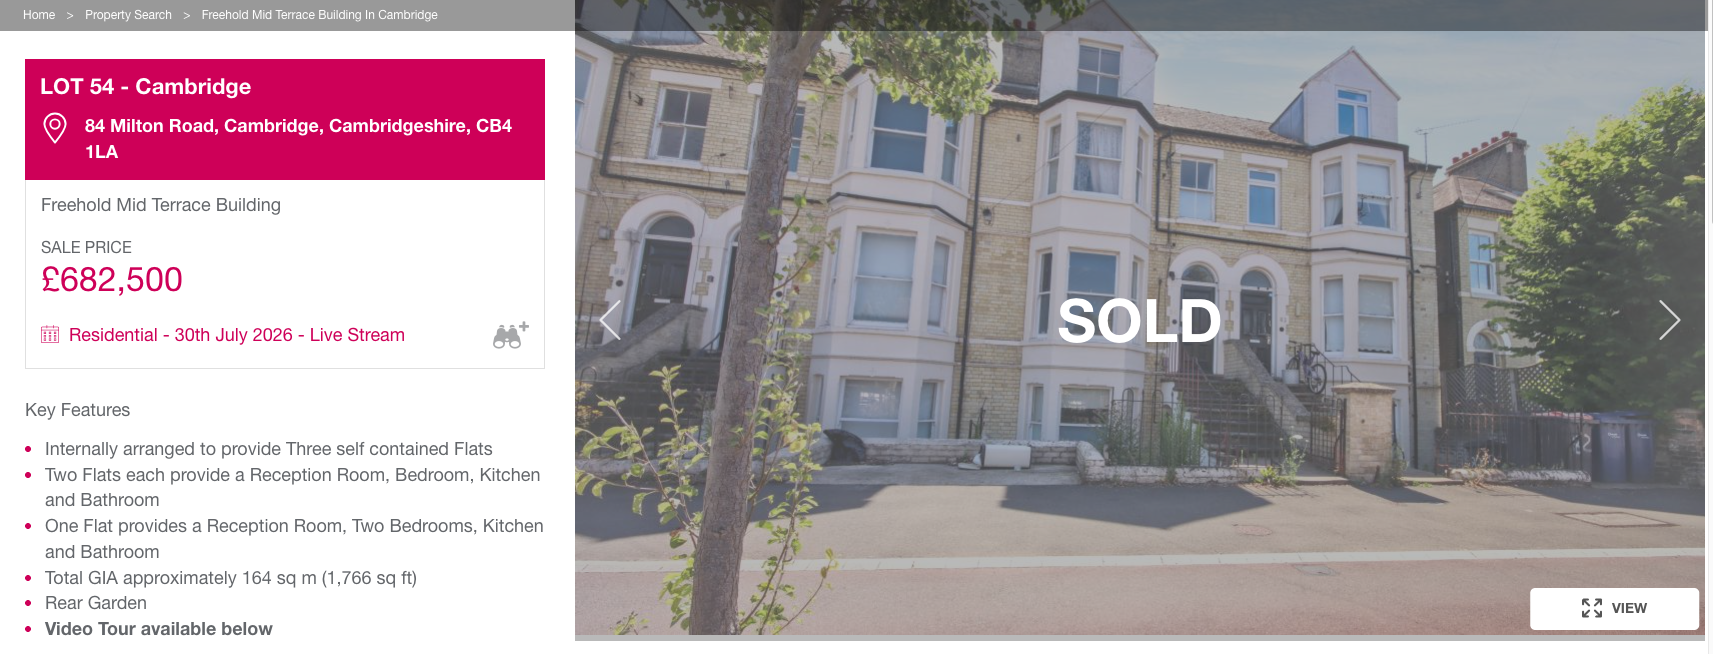
Source: Allsop residential auction, 30 July 2026 (lots 54 & 55).
£570k to buy. £435k is the first charge.
Uses
| Item | £ |
|---|---|
| Purchase price | 525,000 |
| SDLT | 42,500 |
| Legals | 2,500 |
| Total purchase costs | 570,000 |
Sources
| Facility | £ |
|---|---|
| First charge loan, net advance | 435,000 |
| Promoveo and second charge lender, ranking behind | 135,000 |
| Total funding | 570,000 |
No works are started while this loan is outstanding. If route two is needed, planning fees are met by Promoveo and the £165,000 refurbishment is funded by the term and development facilities that repay this loan.
The people behind Promoveo.
Ollie and Jonathan have both built and scaled businesses alongside their property investing. Ollie began investing in buy to let properties in the North East, while Jonathan has over 20 years' experience developing and managing BTL portfolios in Glasgow and Cambridge.
Brendan is a Big Four trained Chartered Accountant with over 25 years' experience across private, listed and private equity backed businesses. He is CFO of a global forensic accountancy firm and owns a portfolio of BTL properties across the South East.
Akaash has over 24 years' experience structuring funding across real estate and corporate transactions. As founder of InvestGrow he has arranged over £260 million in acquisition, development and refinancing facilities, working with lenders, family offices, funds and private investors.